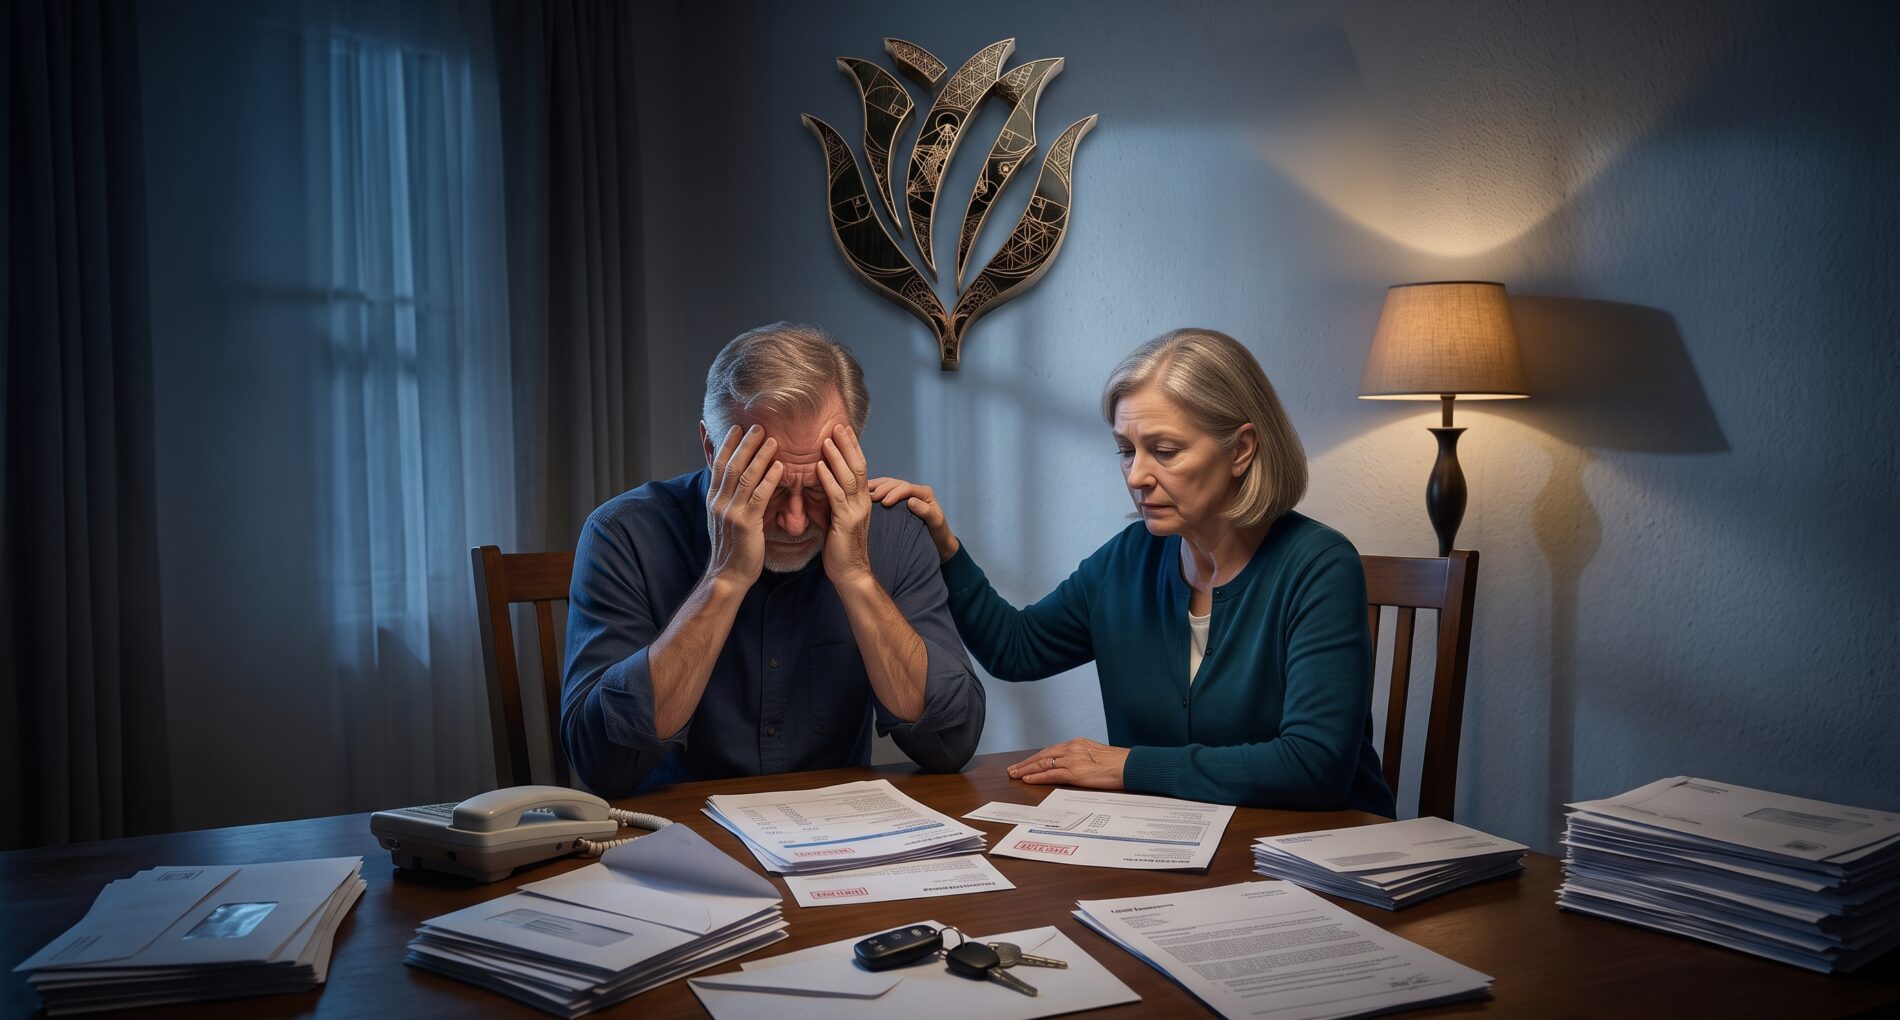
Imagine standing in the fluorescent glare of a grocery store checkout lane. The cashier scans the final item—a gallon of milk for the kids, a few boxes of cereal, the week’s dinners. You swipe your debit card, knowing there should be exactly enough left in the account to cover it until payday. Instead, the machine chimes. Declined. Your stomach drops. You open your banking app on your phone, hands shaking, only to see an unexplained ATM withdrawal made at 2:00 AM. The money is gone.
For families living in the shadow of a loved one’s substance use disorder, this heart-stopping moment is not an anomaly. It is an excruciating, recurring routine.
When we talk about addiction, the conversation naturally and rightfully centers on the emotional and physical toll: the fear of the midnight phone call, the devastating health impacts, the fractured trust, and the desperate hope for recovery. Addiction is a brutal, chronic disease that hijacks the brain’s survival circuitry. It is not a moral failing, a lack of willpower, or a character flaw.
But alongside the emotional wreckage lies another, often unspoken catastrophe—the financial devastation.
For families where one or both parents are battling addiction, the economic reality is a daily exercise in triage. The disease has an insatiable appetite, demanding to be fed before the mortgage, before the electric bill, and before the children’s needs. For the partners, spouses, and family members trying to hold the pieces together, the financial hardship is a heavy, suffocating blanket that colors every single decision they make.
The Direct Bleed: Sustaining the Illness
At its core, active addiction is unfathomably expensive. Depending on the substance, sustaining a daily dependency can cost anywhere from dozens to hundreds of dollars a day. This is a relentless, unyielding expense that forces its way to the top of the household budget.
Because the disease compels the person to seek the substance at all costs, money meant for essentials is inevitably diverted. Joint bank accounts are slowly, or sometimes rapidly, drained. Cash goes missing from wallets. Credit cards are maxed out on cash advances. Valuables—from jewelry to power tools to electronics—quietly disappear from the home, pawned for a fraction of their worth to stave off withdrawal.
The family is left trying to budget around a massive, unpredictable leak. You cannot spreadsheet your way out of active addiction. The non-addicted partner often finds themselves playing a desperate game of financial defense: hiding cash, changing PIN numbers, and rerouting direct deposits just to ensure the lights stay on.
The Collapse of Earning Power
The direct cost of the substance is only the first blow. The second, and often more devastating, is the collapse of the family’s earning power.
Addiction is fundamentally incompatible with the consistency required to maintain employment. It usually begins subtly—a parent calling in sick on a Monday, showing up late, or suffering from reduced productivity and focus. Eventually, warnings turn into suspensions, and suspensions turn into job loss.
When a parent loses their job due to addiction, the household is violently thrust into financial instability. If the family relied on two incomes, the math suddenly stops working. If the addicted parent was the sole breadwinner, the family faces immediate peril. Even if they manage to find new work, the cycle often repeats itself, leading to a resume full of gaps and a gradual slide into lower-paying, precarious employment.
The Tangled Web of Legal and Medical Bills
As the disease progresses, it frequently pulls the legal and medical systems into its orbit—both of which carry exorbitant price tags.
Legal entanglements are distressingly common. A DUI, a possession charge, or a theft arrest triggers a domino effect of expenses. There are bail bonds, impound fees, court costs, mandatory classes, and the staggering hourly rates of defense attorneys. Many families will drain their meager savings or borrow against their 401(k)s to keep their loved one out of jail, driven by the desperate hope that this time will be the wake-up call.
Then come the medical bills. Addiction takes a severe toll on the physical body. Families face the costs of emergency room visits for overdoses, treatment for infections, or hospital stays for withdrawal complications.
And if the person is willing to accept help, the cost of rehabilitation can be paralyzing. While some state-funded or insurance-covered options exist, they often have weeks-long waitlists. Private inpatient rehab facilities can cost tens of thousands of dollars for a 30-day stay. Families routinely take out second mortgages or massive personal loans to pay for treatment, viewing it as a life-or-death investment. Tragically, because relapse is a common symptom of the disease, families often bear these immense costs multiple times.
The Atlas Burden: The Partner Left Holding the Pieces

Behind this financial chaos is the non-addicted partner, bearing an unimaginable weight. They become the household’s sole provider, accountant, and crisis manager.
This partner is forced to absorb the entirety of the financial burden. They take on second jobs or work overtime to cover the deficit left by their spouse. They spend their lunch breaks fielding aggressive calls from debt collectors. They experience the profound, isolating exhaustion of carrying a two-parent household on one set of shoulders.
Furthermore, they carry the guilt and shame associated with financial ruin. In our society, debt and poverty are heavily stigmatized. The non-addicted parent often hides the true extent of the family’s poverty from friends and extended family, suffering in silence to protect their partner’s reputation and preserve a sense of normalcy.
The Collateral Damage: Children and Their Futures
Perhaps the most heartbreaking aspect of this financial crisis is its impact on the children. Kids are incredibly perceptive; they may not understand the intricacies of addiction, but they feel the crushing weight of poverty.
They learn early on not to ask for things. They know there is no money for the school field trip, the soccer cleats, or the senior prom ticket. They listen to the hushed, panicked arguments about money through thin bedroom walls. They feel the anxiety when the electricity is unexpectedly shut off or when dinner consists of whatever is left in the back of the pantry.
The financial strain of parental addiction robs children of opportunities. College funds, if they ever existed, are often drained to pay for rehab or legal fees. The chronic stress of financial and housing insecurity—often moving from house to apartment, or facing eviction—disrupts their education and deeply impacts their psychological development. They inherit a legacy of scarcity that can take a lifetime to unlearn.
The Long Shadow: Credit, Debt, and Housing Instability
Even if the addicted parent enters lasting recovery—a beautiful, hard-won miracle—the financial crater takes years, sometimes decades, to fill.
The collateral damage of addiction leaves behind a long shadow. Credit scores are decimated by missed mortgage payments and defaulted loans, making it nearly impossible to rent a safe apartment, buy a car, or secure a favorable interest rate. Savings accounts are empty. Retirement plans are delayed indefinitely. The family must navigate the fragile early days of recovery while simultaneously digging themselves out of a mountain of debt.
A Path Forward: Hope Without Minimizing
If you are reading this and recognizing your own family in these words, please know this first and foremost: You are not alone, and you are not a bad person for worrying about the money. When a loved one has a life-threatening illness, it feels selfish to worry about bank statements. But financial abuse and ruin are very real symptoms of the disease of addiction. Protecting yourself and your children financially is not a betrayal of your loved one; it is an act of necessary survival.
There is a path forward.
First, establish financial boundaries. It is entirely appropriate to separate bank accounts, lock down your credit, and refuse to co-sign loans or bail your loved one out of jail if it means risking your family’s shelter and food. You cannot cure their addiction by bankrupting yourself.
Second, seek community and professional support. Organizations like Al-Anon, Nar-Anon, and SMART Recovery Family & Friends offer free, profoundly supportive spaces where you can connect with people who understand exactly what you are going through. They can help you navigate the complex emotional landscape of setting boundaries.
For the tangible financial wreckage, seek out non-profit credit counseling agencies (such as those affiliated with the National Foundation for Credit Counseling). They can help you negotiate with creditors, consolidate debt, and create a realistic survival budget without judgment.
Addiction is a thief. It steals health, trust, time, and financial security. The damage is profound and the road to rebuilding is steep. But recovery—both of the spirit and of the bank account—is possible. It begins with lifting the veil of shame, acknowledging the reality of the ledger, and taking the very first step toward reclaiming your family’s future.
burden children credit housing legal medical parental addiction
Last modified: October 2, 2026
When I was first asked to make a film about my nephew, Hubert Farnsworth, I thought \”Why should I?\” Then later, Leela made the film. But if I did make it, you can bet there would have been more topless women on motorcycles. Roll film! I guess because my parents keep telling me to be more ladylike. As though!
Check it out, y\’all. Everyone who was invited is here. Anyhoo, your net-suits will allow you to experience Fry\’s worm infested bowels as if you were actually wriggling through them. And remember, don\’t do anything that affects anything, unless it turns out you were supposed to, in which case, for the love of God, don\’t not do it!