What is a Chargeback? How to Dispute a Credit Card Charge
Learn what a chargeback is, when to use one, and how to successfully dispute card charges when a merchant refuses to issue a refund.
Does disputing a charge hurt your credit?
Worried that disputing a questionable charge on your credit or debit card will hurt your credit score? The short answer is no.
Filing a dispute or chargeback is a protected consumer right handled strictly between you, your bank, and the merchant via the card network. Credit bureaus—Equifax, Experian, and TransUnion—are never notified, and dispute filings do not appear on your credit report.
While the dispute itself cannot harm your score, specific secondary actions can: failing to pay undisputed balances, ignoring re-billed amounts after an unsuccessful dispute, or committing “friendly fraud” through false claims.
Read our comprehensive guide to learn how the dispute process works, how provisional credits temporarily alter credit utilization, and the federal regulations that protect your right to dispute billing errors without penalty.
Strategic Gifting 101: Maximizing Your Personal or Corporate Giving Impact
Giving back is an essential tradition, but writing a check isn’t the only way to make a difference. As year-end approaches, thoughtful philanthropists and forward-thinking businesses are turning to smarter, high-impact giving vehicles that stretch every dollar further.
In our practical primer, Strategic Gifting 101, we break down how to optimize your charitable contributions while maximizing personal or corporate tax efficiency. Discover how Donor-Advised Funds (DAFs) unlock the power of “tax bunching,” learn how to leverage corporate volunteer matching to instantly double your community footprint, and explore the benefits of gifting appreciated securities over cash.
Whether you are planning an individual gift or steering a corporate CSR strategy, smart giving builds sustainable lifelines for individuals reclaiming independence after addiction. Explore the side-by-side comparison matrix and discover how intentional planning turns seasonal generosity into generational stability.
Unauthorized charges on your PayPal account? Here’s how to get your money back now
Ben Castellano was stunned to find $1,180 in unauthorized charges on his PayPal account. Even though he had no idea who made the transfers, PayPal refused to reverse the transactions, claiming the “Sending to a friend” feature used by the scammers wasn’t protected under its terms of service. Adding insult to injury, PayPal told Castellano he should use a different payment method “next time,” despite the fact he never sent the money in the first place.
Castellano’s frustrating ordeal shines a light on the often confusing and opaque inner workings of PayPal’s dispute resolution system. How does a user successfully dispute a fraudulent charge? What are your options when an initial appeal is denied, and what kind of explanation does PayPal owe its customers? Read on to learn how these unauthorized charges happened—and what you can do if you ever find your own account compromised.Ben Castellano was stunned to find $1,180 in unauthorized charges on his PayPal account. Even though he had no idea who made the transfers, PayPal initially refused to reverse the transactions. The company claimed the “Sending to a friend” feature used by the scammers wasn’t covered by its Purchase Protection under its terms of service. Adding insult to injury, PayPal told Castellano he should use a different payment method “next time,” despite the fact he never authorized the money transfers in the first place.
Castellano’s frustrating ordeal shines a light on the often confusing and opaque inner workings of PayPal’s dispute resolution system. How does a user successfully dispute a fraudulent charge? What are your options when an initial appeal is denied, and what kind of explanation does PayPal owe its customers? Read on to learn how these unauthorized charges happened—and what steps you can take if you ever find your own account compromised.
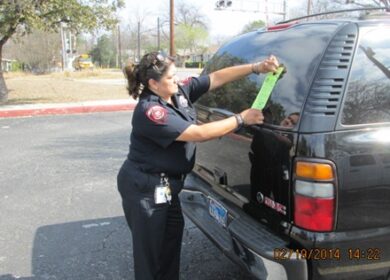
San Antonio, Municipal Codes, Officer, and your rights.
“Administrative code compliance cannot bypass closed security perimeters to conduct warrantless searches. When city officials step outside the law to enforce the law, the resulting actions lack legal standing.”
Protected Perimeter: Completely enclosed by an authorized 6-foot temporary security fence to keep pedestrians safe from an active post-demolition site.
Zero Street Visibility: Alleged code violations were physically impossible to observe from any public street, sidewalk, or alleyway.
Captured on Video: Surveillance footage confirms repeated, unauthorized entry past private safety barriers without an administrative warrant.
Legal Shielding: Under the Fourth Amendment (Camara v. Municipal Court) and Texas Code of Criminal Procedure Art. 38.23, evidence obtained via warrantless intrusion onto protected curtilage is constitutionally invalid.
Can your HOA foreclose on your house? Yes. And you can still owe on the loan.
Yes, an HOA can foreclose on your house. If you fall behind on dues, it can put a lien on the house and, depending on your state, sell it, sometimes without a judge. Losing the house doesn’t erase your mortgage, so you can still owe the bank. If you get a lien or foreclosure letter, call a lawyer that day.
New Data Shows a Very Human Problem: People Get Burned Every Day, Then Stay Quiet About It
Have you ever felt swindled by a contractor, mover, or hidden fee, only to swallow the cost because you felt embarrassed? You aren’t alone. According to the LegalShield Shame Gap study, 75% of Americans have felt taken advantage of in the marketplace, yet over half stay quiet due to self-blame.
When a service provider changes the price after the truck is loaded or fails to fix a problem they charged you for, the financial hit is only part of the sting. The real burden is the quiet shame that follows—wondering if you missed something obvious or trusted the wrong person. This self-doubt frequently prevents consumers from seeking help, with 66% of people stating that not knowing what to say to a lawyer is a major hurdle.
However, you don’t need a polished story, a perfect folder of evidence, or an extensive legal vocabulary to ask if you’ve been wronged. Real consumer problems are messy because real life is messy. If something feels off or a deal changes halfway through, don’t brush it off as “just life” or assume your problem is too small to matter. Stop blaming yourself long enough to ask questions and get clarity. You are not foolish, and you definitely aren’t the first person this has happened to. Read the full article to learn how to move past the shame gap and advocate for yourself.
Managing Record Household Debt: Lessons from the LegalShield Stress Index
While national headlines often point to “resilient consumer spending” as a sign of a healthy economy, our latest LegalShield Consumer Stress Legal Index (CSLI) tells a much different story.
The reality? American households are increasingly using credit cards and “Buy Now, Pay Later” services to mask a deepening debt crisis.
These 7 phrases will doom your consumer complaint.